How AP Injury Lawyers Helps After an Oklahoma City Crash
After a car accident in Oklahoma City, many injured people focus first on who caused the crash. Fault matters, but insurance coverage can determine how much compensation is actually available.
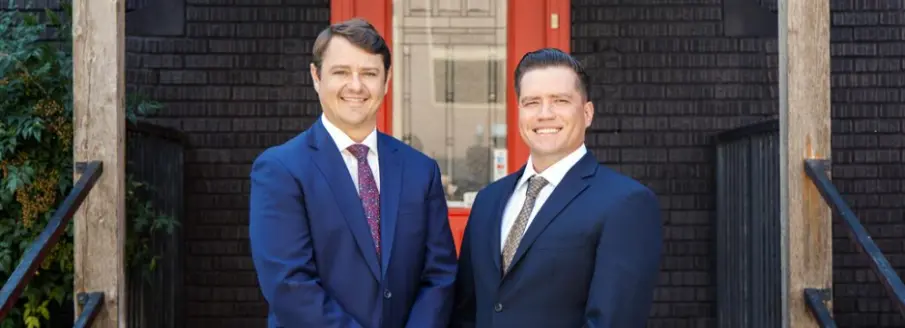
AP Injury Lawyers handle personal injury and car accident claims in Oklahoma City and across Oklahoma County. One of the first questions the firm's lawyers examine is how much insurance coverage exists and which policies may apply. This approach to legal representation can uncover coverage that is easy to miss after a serious collision.
The firm operates from 2248 NW 40th Street in Oklahoma City and handles crashes involving cars, motorcycles, pedestrians, cyclists, impaired drivers, and rideshare vehicles.
Is There Enough Insurance to Cover the Injuries?
Sometimes there is not.
Oklahoma requires minimum auto liability coverage of 25/50/25. That means $25,000 for bodily injury to one person, $50,000 for bodily injuries in one accident, and $25,000 for property damage. The Oklahoma Insurance Department notes that these minimum limits may not be enough when medical treatment, lost income, and other losses become substantial.
A serious injury can quickly create losses that go beyond a $25,000 policy limit. That is why an insurance investigation should look beyond the at-fault driver's policy.
Potential sources of coverage may include the at-fault driver's liability policy, the injured person's uninsured or underinsured motorist coverage, an employer's commercial policy, a vehicle owner's policy, or other applicable coverage. Medical payments coverage may also help with medical expenses when it is included in the policy.
Rideshare collisions can involve additional insurance questions. Depending on what the driver was doing at the time of the crash, coverage from the driver's personal policy and the rideshare company's policy may need to be examined.
What Happens When the Other Driver Has No Insurance?
Uninsured motorist coverage can become important when the driver responsible for a crash has no insurance. Underinsured motorist coverage can also apply when the at-fault driver's available limits are not enough to cover the injured person's losses.
The Oklahoma Insurance Department explains that UM or UIM coverage can apply to injuries caused by an uninsured or underinsured driver, including certain hit-and-run situations. Oklahoma also allows policyholders to reject this coverage in writing, making the insurance declarations page an important document to review.
That document can show coverage limits that do not appear on a standard insurance card. For someone who has been injured, checking the declarations page may reveal an additional source of compensation.
A UM or UIM claim is also made against the injured person's own insurance company. That can surprise people who have paid premiums to the same insurer for years. The claim still needs to be supported with evidence of liability, injuries, medical treatment, and financial losses.
How Long Does a Car Accident Claim Take in Oklahoma?
Oklahoma generally provides a two-year limitation period for personal injury actions. Claims involving property damage are also generally subject to a two-year limitation period.
Claims involving government entities can follow different rules. Under the Oklahoma Governmental Tort Claims Act, a claim generally must be presented within one year after the loss occurs. That can matter when a collision involves a city, county, state agency, public transit vehicle, or another government-related entity.
The legal deadline is not the only reason to act promptly. Evidence can disappear long before a lawsuit deadline. Security footage may be overwritten, vehicles can be repaired or sold, and physical evidence at the crash scene may no longer be available.
Witness memories can also fade. A person who clearly remembers the traffic signal, lane positions, weather, or the driver's actions immediately after a collision may provide useful evidence later in the claim.
What About Shared Fault?
Oklahoma follows comparative negligence rules. An injured person's compensation can be reduced based on that person's share of fault. Oklahoma law also limits recovery when the claimant's negligence is greater than the negligence of the opposing party or the combined negligence of multiple responsible parties.
Insurance companies may therefore ask questions about speed, visibility, road conditions, attention, or what happened immediately before impact. Even statements that seem harmless can become part of the claim file.
Questions such as whether someone was speeding, whether they saw the other vehicle in time, or whether they had any previous pain can affect how an insurer views responsibility and damages.
An injured person should also be careful about social media posts after a collision. Photos or comments that appear unrelated to the accident can sometimes be taken out of context and used to challenge the severity of an injury.
Why Insurance Review Matters Early
A strong liability claim does not automatically mean that enough insurance exists to pay for every loss. Medical expenses, lost wages, property damage, rehabilitation, and other costs can quickly exceed minimum policy limits.
That is why the insurance investigation deserves attention early in the process. Lawyers may need to determine whether multiple policies apply, whether uninsured or underinsured motorist coverage is available, whether an employer could have responsibility, or whether a rideshare policy may provide additional coverage.
People researching legal options after a crash can also review an Oklahoma City attorney listing for additional firm information.
For people injured in Oklahoma City crashes, understanding the available insurance can provide a clearer picture of what the claim may involve before an insurance settlement is accepted. AP Injury Lawyers handle personal injury and car accident matters across Oklahoma County, with attention to both liability and the insurance coverage that may ultimately determine recovery.
More to Read:
Previous Posts: